Fannie Mae and Freddie Mac are rolling out a new set of rules aimed at making condos safer. But they come with some extra caveats that would-be condo owners ought to know.This week, the Federal Housing Finance Agency enacted a set of rules announced in March that change insurance requirements for condominium buildings and communities. The new rules require more thorough reviews of a condo association's finances, as well as the building's condition.The new rules also mandate that condo associations carry more reserves for maintenance.FHFA Director William Pulte said the goal was to reduce insurance and other costs, and give buyers "confidence that they can afford the American dream."But Realtor.com® senior economist Joel Berner says the changes also mean it might take a little longer to obtain a mortgage, and there is a risk of higher denial rates. "Where before, purchases were authorized with limited review of a condo association's budget, reserves, insurance, and litigation history. Now, under the required full review, more issues will crop up causing delays and denials," Berner says."Condo associations and lenders are not used to being required to provide all this paperwork," he ...
Fannie and Freddie’s New Condo Mortgage Rules Could Mean More Delays and Denials, Experts Say
 1 month ago
35
Related

Beekeeper lands $200,000 windfall for Fitzroy townhouse
9 hours ago
5


Inside $4.5m Melb home built around Italian marble
12 hours ago
6

Court battle over top Sydney celeb trophy home
12 hours ago
4


Inside shock $9k bathroom reno
12 hours ago
6

Major update on man who lost home over unpaid bills
12 hours ago
6
Popular
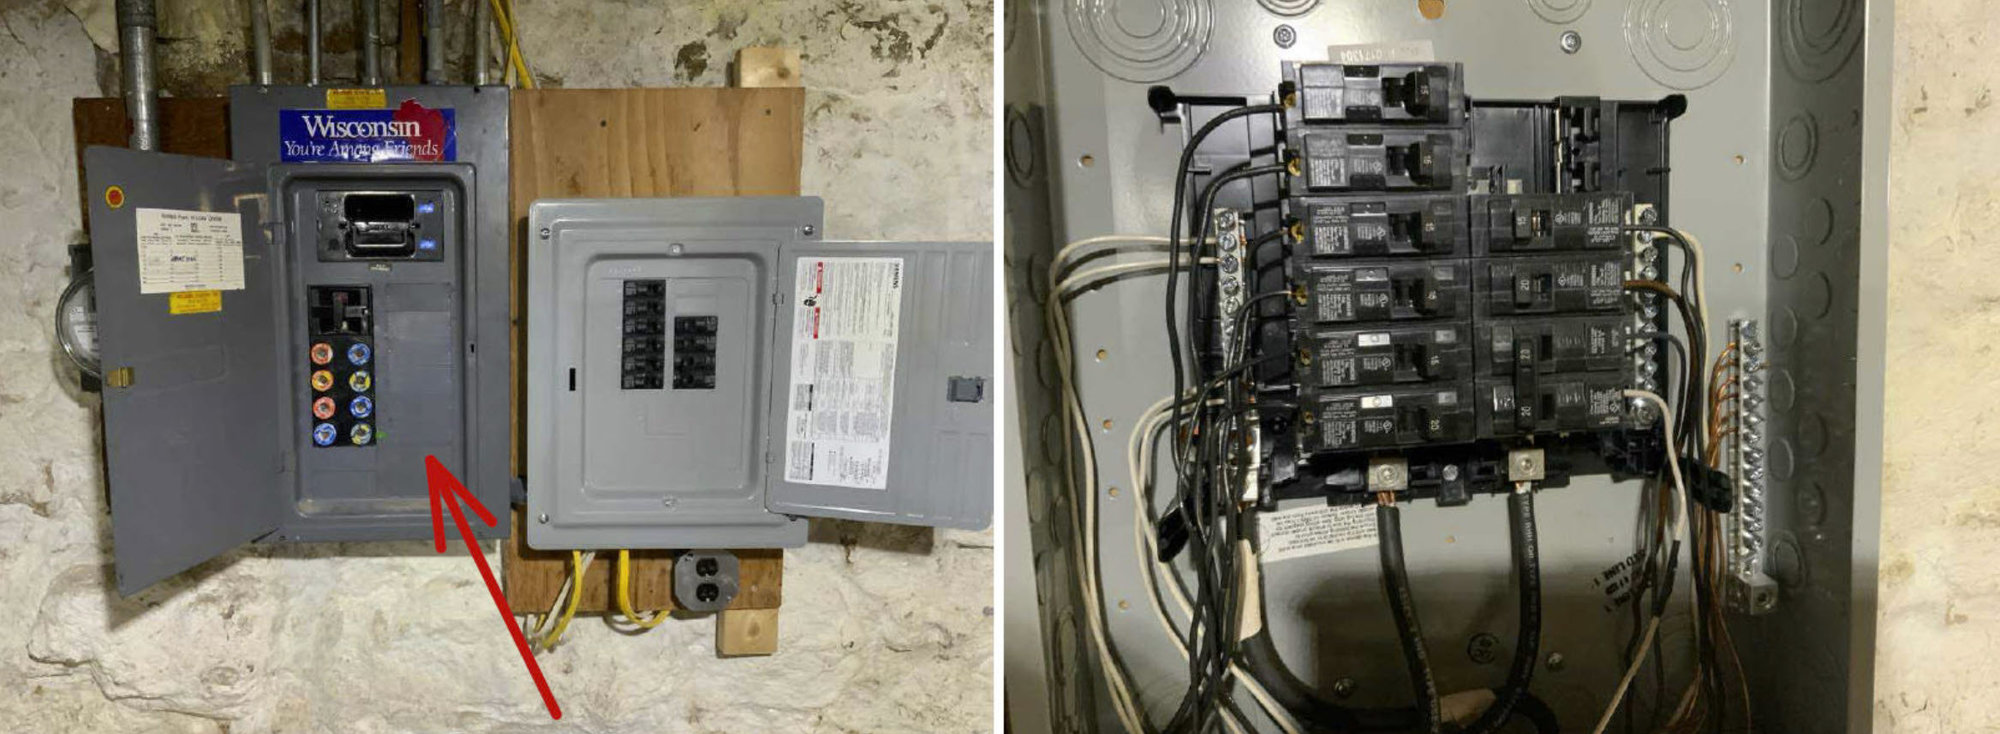
The $5,000 question: How much will those repairs cost?
4 weeks ago
54

MBA mortgage applications dip 1% as refinance slips 2%
3 weeks ago
51

What can the government do to lower mortgage rates?
1 month ago
50

Back in business: Knight Frank, McGrath join forces
2 weeks ago
47

 English (US) ·
© Clint's Real Estate 2026. All rights are reserved
