For decades, the Agency Mortgage-Backed Securities (MBS) market operated on an implicit, foundational constant: a loan’s representative credit score meant Classic FICO. Capital markets desks built trading algorithms around it, risk engines calibrated duration based on it and specified pool buyers paid billions in pay-ups resting on their predictable prepayment behavior. That baseline is shifting. Recent government-sponsored enterprise (GSE) pool data reveals an emerging trend that demands the immediate attention of secondary marketing desks, desk traders and portfolio managers: A growing percentage of loans in newly issued Fannie Mae and Freddie Mac pools are underwritten using VantageScore 4.0 (VS4). While the Federal Housing Finance Agency (FHFA) framed its credit modernization initiative as a step toward expanding homeownership, allowing approved lenders to choose between Classic FICO and VS4 on a loan-by-loan basis introduces structural shifts into the secondary market. What is intended to be an operational update for primary originations is becoming a complex valuation problem for the secondary market. The illusion of equivalence To the uninitiated, replacing a 720 Classic FIC...
The unseen shift in agency pools: How ‘lender choice’ is quietly repricing specified pools
 2 days ago
6
Related
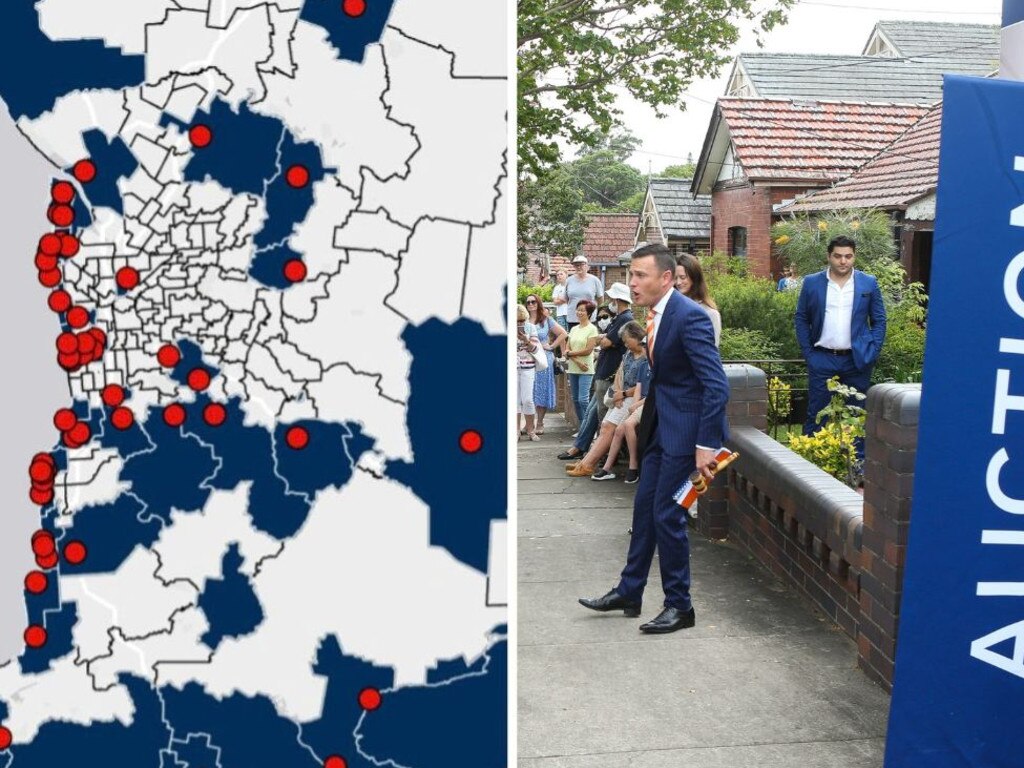
Sydney’s great house and unit divide
15 hours ago
8


Popular

TWO wins final regulatory approval for CCM deal
4 weeks ago
59
Mark Zuckerberg buys an Irish castle
4 weeks ago
57

Spec House 101: What to Know Before Buying
4 weeks ago
49
The $5,000 question: How much will those repairs cost?
3 weeks ago
49


What can the government do to lower mortgage rates?
4 weeks ago
48

MBA mortgage applications dip 1% as refinance slips 2%
3 weeks ago
47
 English (US) ·
© Clint's Real Estate 2026. All rights are reserved
