At first glance, a 9% annual yield can make buying a vacation home sound like a pretty compelling investment.The headline number, from AirDNA, sits within the 7% to 10% long-term annual return some experts use for diversified U.S. stocks—and is nearly twice the 4.73% yield on a 10-year Treasury in late August.But it’s not the same thing as a net investment return. Instead, the figure represents projected rental revenue relative to a property’s purchase price before many of the costs required to own and operate the home.The problem for vacation-home owners is that one of those bills is becoming harder and harder to predict.A first-of-its-kind analysis released in August by the National Association of Insurance Commissioners (NAIC) found that, even after adjusting for inflation, average premiums per policy rose in all four regions it studied between 2018 and 2024—from 18.3% in the Northeast to 43.3% in the West.Over the same period, insurer-initiated nonrenewal rates increased 96% to 216%, depending on the region.The best vacation markets can carry some of the biggest risksIn its report, the NAIC pointed to a fairly straightforward explanation for those startling numbers: Insurers ar...
The True Carrying Cost of Vacation Homes: How Insurance Is Eating Second-Home Yields
 3 weeks ago
22
Related

Beekeeper lands $200,000 windfall for Fitzroy townhouse
11 hours ago
6


Inside $4.5m Melb home built around Italian marble
14 hours ago
7

Court battle over top Sydney celeb trophy home
15 hours ago
5


Inside shock $9k bathroom reno
15 hours ago
7

Major update on man who lost home over unpaid bills
15 hours ago
7
Popular
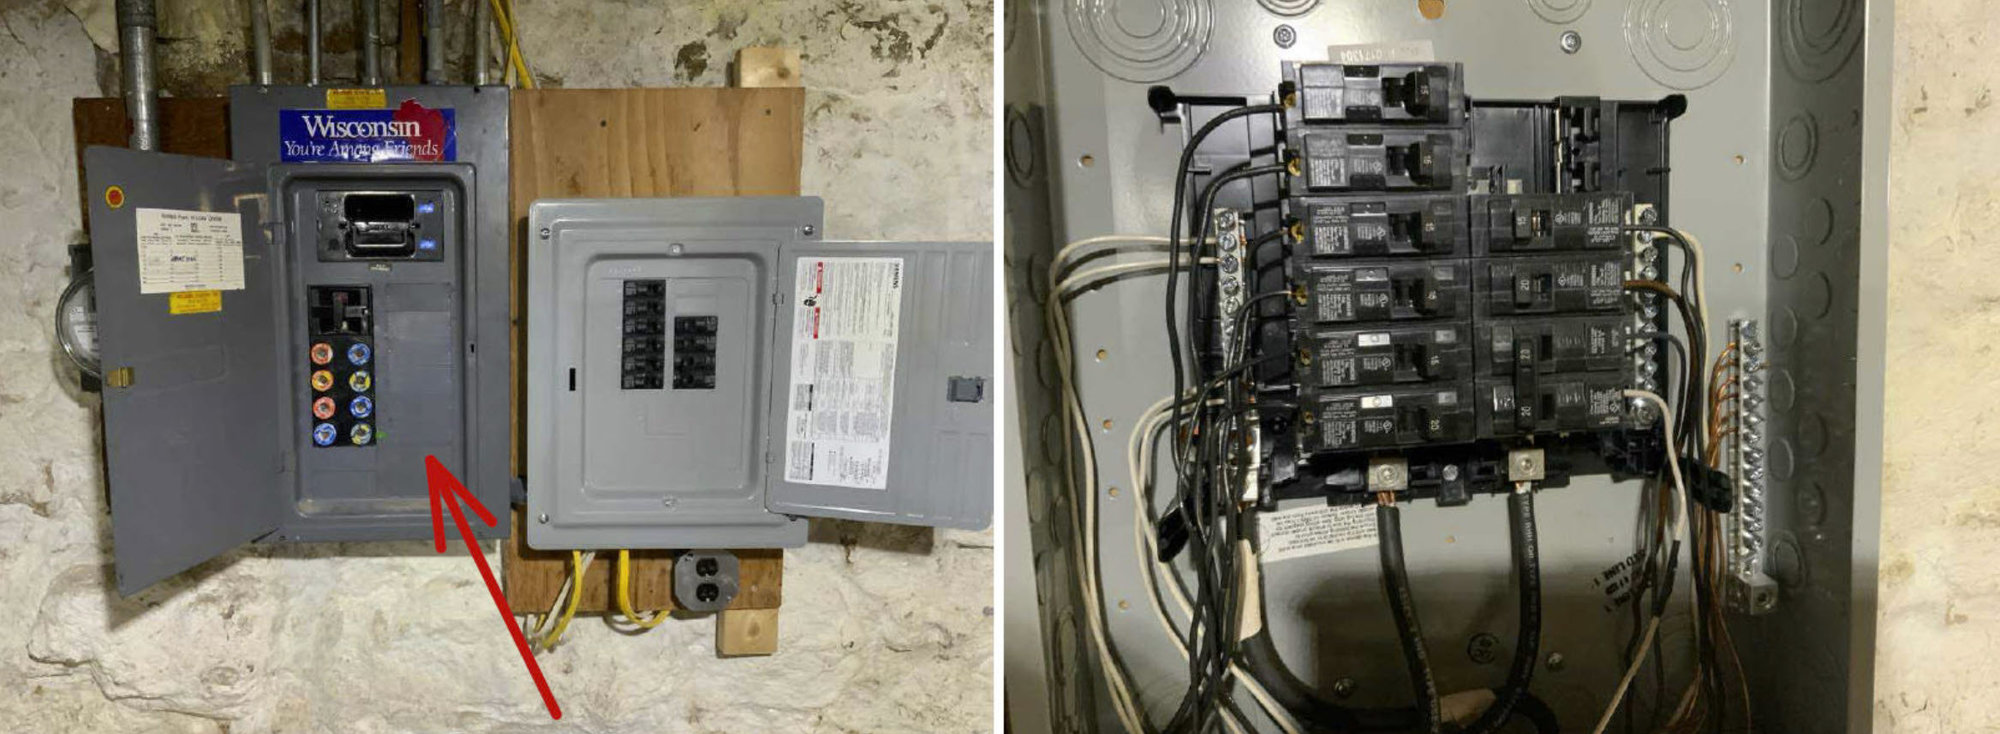
The $5,000 question: How much will those repairs cost?
4 weeks ago
54

MBA mortgage applications dip 1% as refinance slips 2%
3 weeks ago
51

What can the government do to lower mortgage rates?
1 month ago
50

Back in business: Knight Frank, McGrath join forces
2 weeks ago
47

 English (US) ·
© Clint's Real Estate 2026. All rights are reserved
