Mortgage banking has always been cyclical. This cycle has been unforgiving. Rates remain high, affordability is strained, inventory is tight and refinance volume has been slow to return. It may seem easy to wait for a better market. That may be the wrong focus. The case for waiting deserves scrutiny against current data rather than the memory of prior cycles. As of this writing, Freddie Mac reports the 30-year fixed rate at 6.66%, higher than one year ago, after reaching 6.69% in early August, the highest weekly average of 2026, following five consecutive weekly increases. Pending home sales have fallen to their lowest level since January. The median existing-home price has risen for 37 consecutive months. The Mortgage Bankers Association’s July forecast projects total originations of roughly $2.2 trillion in each of 2026, 2027 and 2028, with the 30-year rate near 6.5% throughout the period. Each prior downturn, including 2010 through 2012, the refinance collapse of 2013 and 2014 and the margin compression of 2018, produced predictions of structural change, and each was interrupted by a rate rally before the structure itself changed. The current forecast contains no comparable reli...
Into the crucible: Five questions every residential lending CEO should answer
 1 week ago
12
Related
Australia’s housing crisis deepens as new home sales plunge ...
49 minutes ago
3
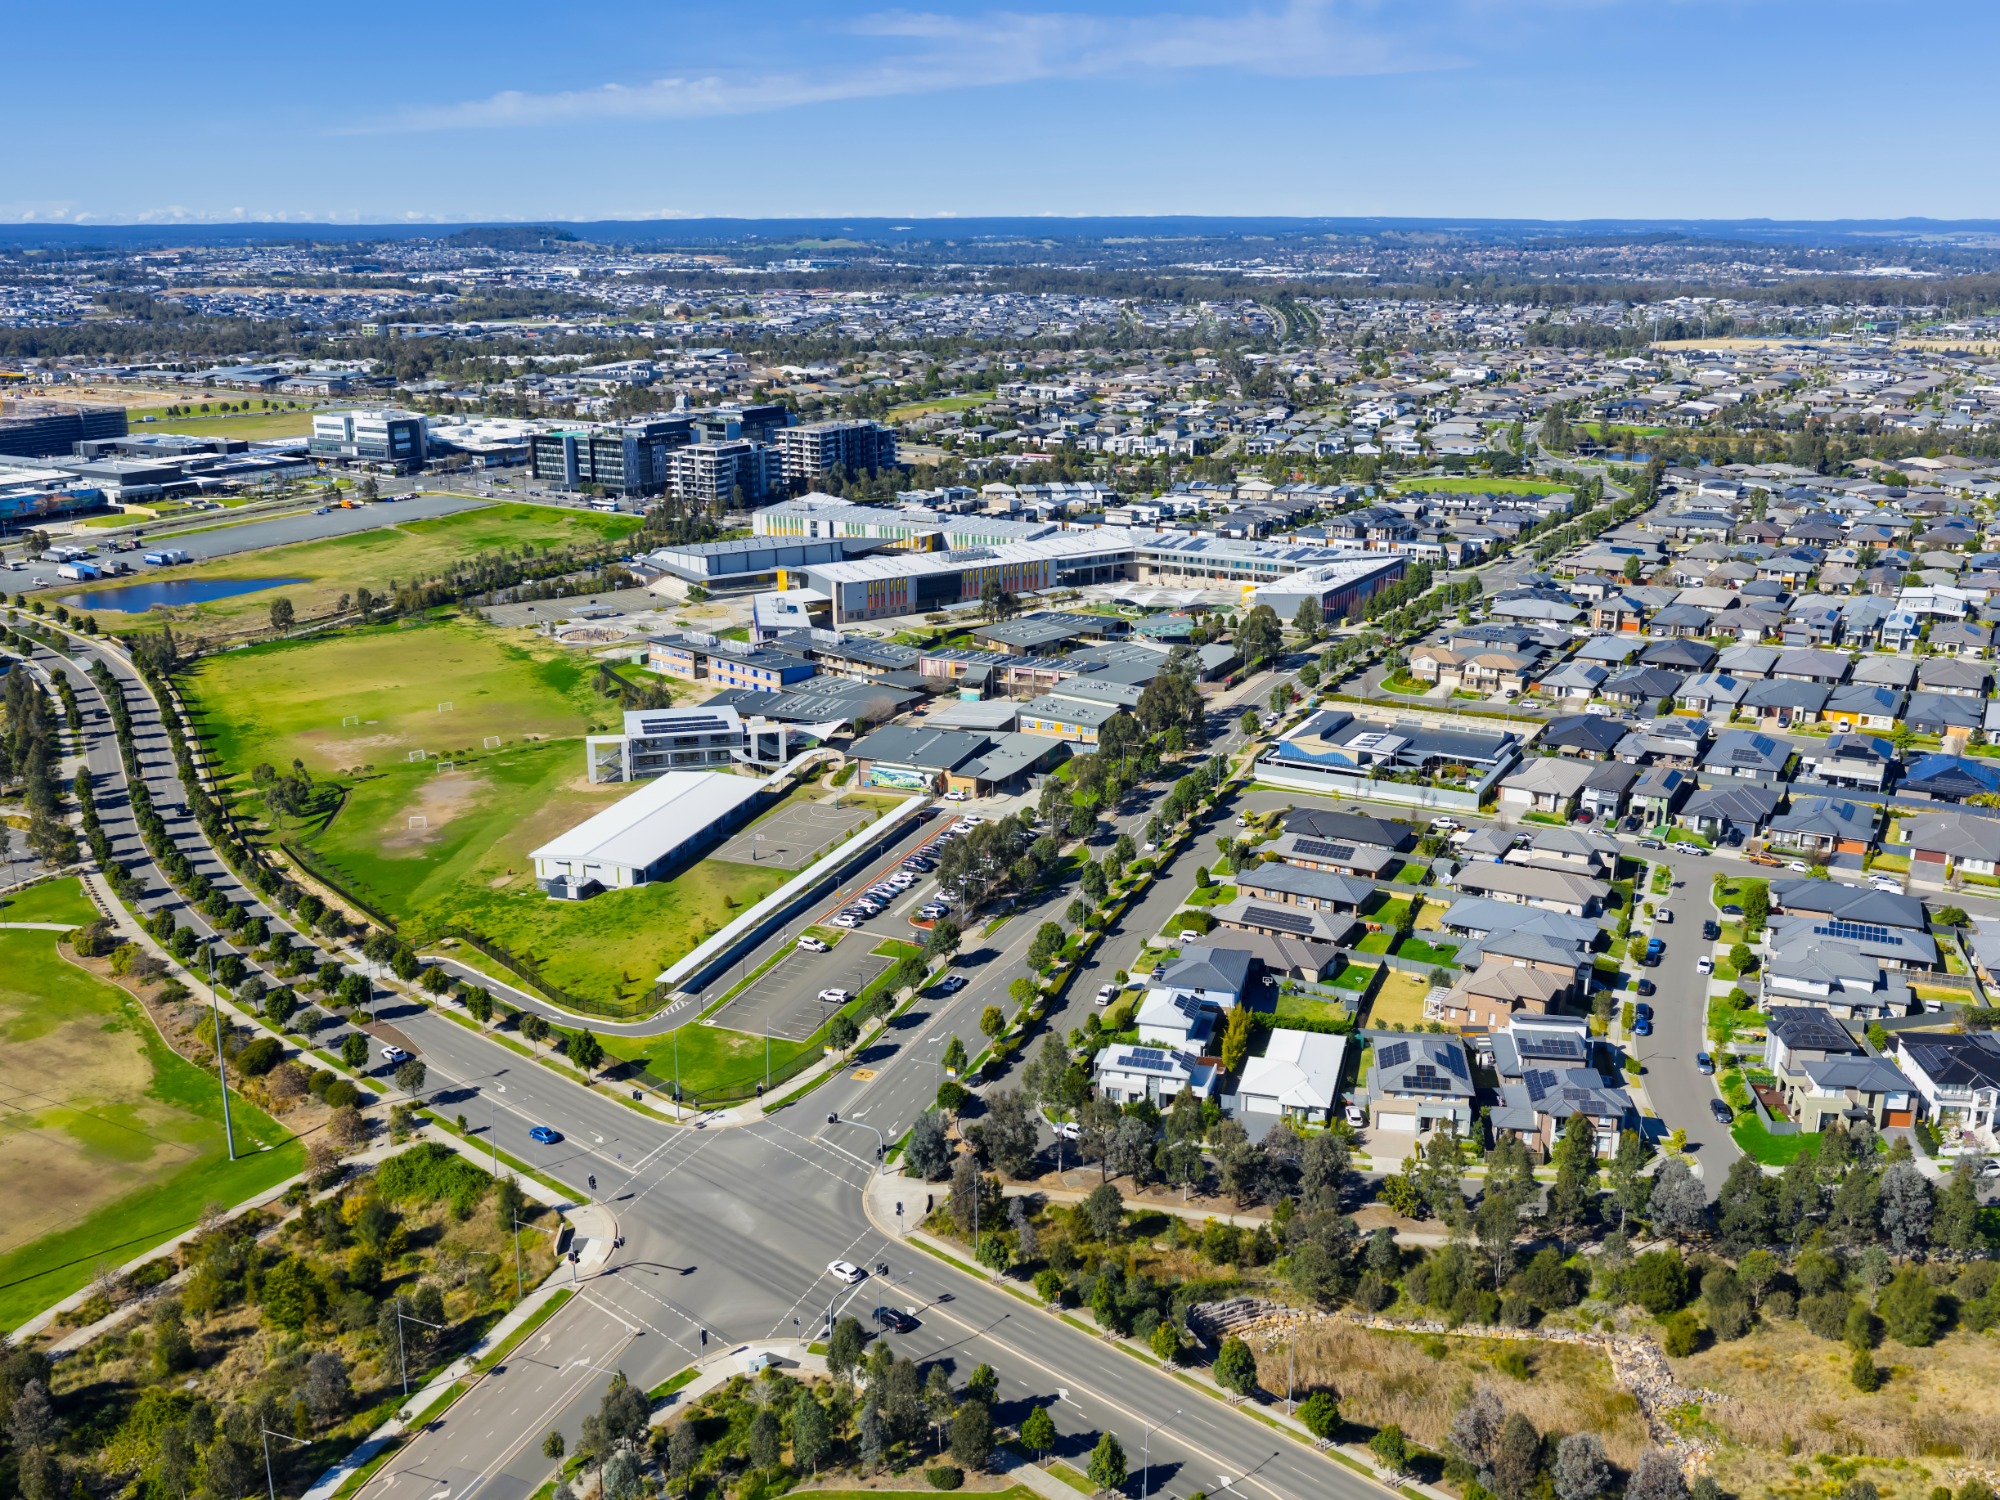
Where master-planned living is booming across Australia
2 hours ago
1

Phillip Island Block home sells $2.2m below Portelli
3 hours ago
2

Popular

TWO wins final regulatory approval for CCM deal
3 weeks ago
48


Mark Zuckerberg buys an Irish castle
3 weeks ago
45

Real names Jenna Rozenblat president of Real REMAX Group
3 weeks ago
45


 English (US) ·
© Clint's Real Estate 2026. All rights are reserved
